1. Fundraising: why raise?
Fundraising typically happens at a key moment in a company’s life, when the business needs to execute a structured plan that requires a level of investment that cannot be covered by operating cash flow or a standard bank loan.
That plan might be the launch of a new product, scaling commercial execution, expanding internationally, or making heavy technology investments. In that context, fundraising means financing the costs of the plan while giving investors clear growth projections and value-creation assumptions.
It’s essential to understand that you don’t raise money without a clearly identified project and a precise estimate of its cost. One of the fastest ways to jeopardize a round is to take an opportunistic approach, assuming the roadmap will be defined after you see how much capital you manage to raise. Investors expect the opposite: a clear, structured, quantified plan.
Likewise, a fundraising round whose primary objective is to finance founders’ salaries, without a credible expansion or development thesis, is typically poorly received. Investors invest first and foremost in value-creating projects, not in maintaining the status quo.
2. The main stages of fundraising
2.1 Estimate your funding needs
The first step in any fundraising process is to define your funding needs precisely. This requires a clear roadmap that sets the plan’s objectives, milestones, and the time horizon you’re operating on.
You then need to estimate all associated costs and investments: hiring, product or technology development, marketing spend, operating overhead, and any tangible or intangible investments. These estimates must be realistic and consistent with the company’s maturity.
Beyond direct investment, you also need to account for the cash tied up in working capital (receivables and inventory minus payables). Customer payment terms and inventory build, set against the terms you get from suppliers, can create meaningful cash burn.
Finally, some growth phases imply temporary losses during ramp-up. Those should be anticipated and incorporated into the financing plan to avoid liquidity stress mid-execution. Only projected statements that tie income, cash and balance sheet together show in which month that cash trough bottoms out, and that low point, not the annual loss, is what the amount raised must cover.
Once that number is set, it has to be turned into a slide investors can read: the rule is to cover 18 to 24 months of runway and reach the milestones of the next round. Our guide explains how to present your use of funds without giving the impression the amount was picked at random.
2.2 Preparation: the most decisive phase
Preparation is arguably the most important phase for a successful round. Its goal is to reduce the uncertainty perceived by investors and financing partners, by presenting a coherent, well-documented, and execution-ready plan.
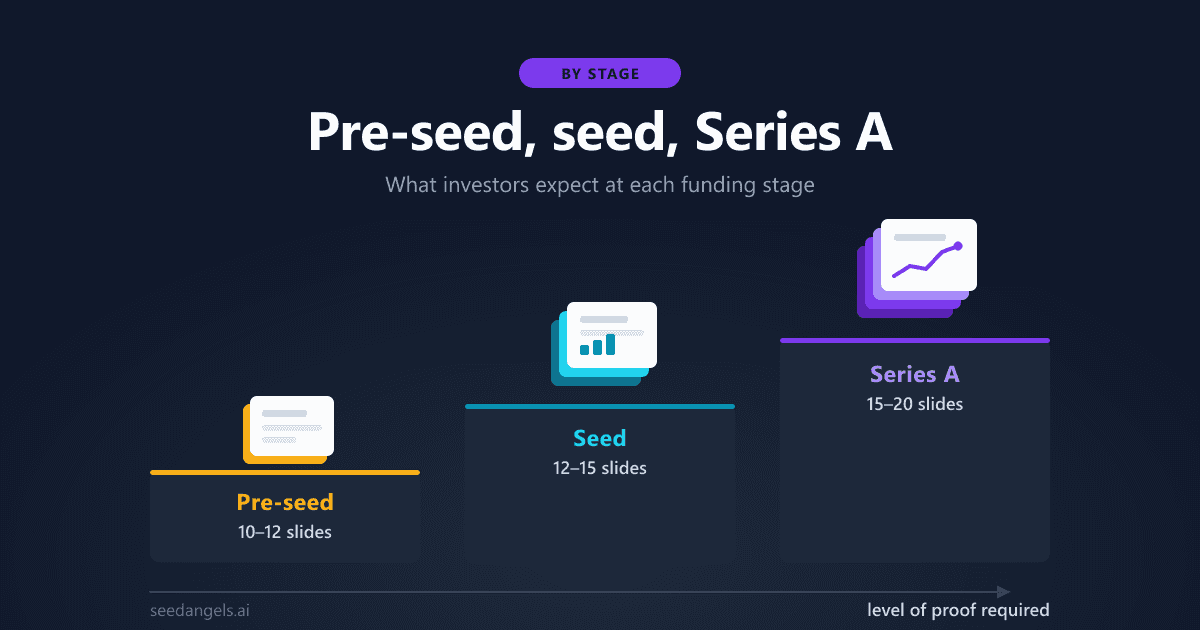
It starts with building the core fundraising materials: a concise teaser and a structured Pitch Deck that clearly explain the project, the market, the business model, and the team. What that deck is expected to contain differs depending on whether you are raising a pre-seed or a Series A: check the pitch deck expected at your stage before you start writing it. Once your deck is drafted, run it through our free Pitch Deck Analyzer to see how it scores on a 34-criterion grid modelled on an investor's analysis. In parallel, you should build a data room to centralize the financial, legal, and operational documents investors will require.
A complete, credible Business Plan sits at the heart of this preparation. For inspiration, browse our free Business Plan templates and examples, real AI-generated documents covering several sectors, downloadable in Word and PDF. You can also generate your Business Plan with AI to save time on this decisive step.
This phase also includes a deep reflection on company valuation and the resulting dilution for founders. It’s crucial to understand the short- and long-term implications. Use our free startup valuation calculator to model your pre-money / post-money valuation, and our dilution calculator to see exactly how much equity you'll give up at each round.
You should also anticipate the type of securities offered (common shares, preferred shares, or hybrid instruments) and the rights granted to minority investors: information rights (periodic reporting), governance rights, and liquidity protections, usually set out in the shareholders' agreement.
Finally, preparation means defining your fundraising timeline, selecting advisors (especially legal counsel), identifying target investors, and practicing the pitch until it is crisp, consistent, and convincing.
2.3 Investor outreach and roadshow
Once preparation is complete, the company can begin investor outreach. This often relies on networks, qualified introductions, or direct outreach.
Your narrative should be adapted to each investor profile, taking into account their track record, investment criteria, and expectations. Repeated meetings help collect feedback, identify objections, and, when needed, refine elements of the plan or the presentation.
A deck rarely gets a second chance with the same investor, so it is far better to fix the deck mistakes to avoid before sending than to discover the problem after a string of unexplained passes.
2.4 Letter of intent
When discussions progress positively, a letter of intent (often called a term sheet) is typically issued. This document frames the deal’s main terms: valuation, amount invested, instrument type, and key investor rights.
Even when some clauses are non-binding, the term sheet is a structuring milestone in the fundraising process.
2.5 Due diligence
Due diligence allows investors to verify that what was presented matches the reality of the business. It typically covers financial, legal, and operational topics.
This phase relies on transparency and consistency. Any inconsistency or approximation can weaken trust and jeopardize the transaction.
2.6 Negotiating the bylaws and shareholders' agreement
Once due diligence is completed, discussions shift to negotiating the company's articles/bylaws and the shareholders' agreement. These documents formalize the relationship between founders and investors.
They define governance rules, liquidity rights, investor protections, and mutual commitments. The objective is to find a balance between investor protection and founders’ ability to execute.
2.7 Closing
Closing is the finalization of the transaction. It includes signing the legal documentation, releasing the funds, and, when relevant, communicating publicly about the round.
3. Financing instruments
Choosing the right financing instrument is a structuring decision in any fundraising round. Each instrument comes with a different dilution profile, rights package, and risk-return trade-off for the investor. Understanding your options is essential before finalizing a fundraising strategy.
3.1 Non-dilutive financing
Non-dilutive financing can fund part (or sometimes most) of a plan without opening the company’s equity. It is often attractive at early stages, but tends to be constrained in amounts and permitted use.
Main categories include:
-
Grants
Non-repayable funding, often designed to support innovation, R&D, or strategic sectors.
Benefit: no dilution and no repayment.
Limitation: long processes, strict criteria, and sometimes limited amounts. -
Repayable advances
Public or quasi-public funding repaid on a schedule set in the contract; if the funder formally recognises that the project has failed, repayment can be waived in whole or in part.
Benefit: risk-sharing with the funding body.
Limitation: future repayment that can impact cash runway. -
Traditional bank debt
Loans granted by banks, typically conditional on:- proven repayment capacity,
- personal or asset guarantees.
Benefit: no dilution.
Limitation: often hard to access for young or highly innovative companies.
-
Innovation debt / venture debt
Debt instruments adapted to startups, sometimes with fewer guarantees but higher cost.
Benefit: leverage without immediate dilution.
Limitation: increases financial risk if growth does not materialize.
The schemes to know in 2026
Each country runs its own programmes, but a few large ones show what non-dilutive money looks like for a startup. Amounts checked on the official pages on October 19, 2026:
| Scheme | Form | Maximum amount | Who it is for |
|---|---|---|---|
| SBIR / STTR (United States) | Federal R&D awards | $335,937 in Phase I, $2,239,578 in Phase II (without an SBA waiver) | US small businesses with an R&D project, through 11 federal agencies |
| EIC Accelerator (European Union) | Lump-sum grant, optional equity | Grant below €2.5 million, investment from €1 to €10 million | Startups and SMEs in the EU and Horizon Europe associated countries |
| Bourse French Tech (France, Bpifrance) | Grant | €30,000 | SMEs with an innovation project at the maturation or feasibility stage |
| SBA Microloan (United States) | Loan through nonprofit intermediaries | $50,000 (average about $13,000) | Small businesses and startups that need a small first loan |
A few points that change how you build the application:
- Grants rarely cover the full budget. The EIC Accelerator grant funds technology at a late development stage (TRL 6 to 8) over 24 months, and UK applicants can only apply for the grant-only scheme. In France, the Bourse French Tech covers up to 50% of eligible costs, or up to 70% depending on the company category, and no cost incurred before the application date is eligible. Plan your co-financing before you apply.
- Programmes can pause. SBIR and STTR lapsed on September 30, 2025, when Congress did not renew them in time, and were reauthorized in April 2026 through 2031. A grant that is open today may be closed when you need it: always check the official page before counting a scheme in your funding plan.
- Repayable advances and personal loans exist too. Some agencies fund risky innovation through advances repaid only if the project succeeds, and some networks lend directly to the founder at zero interest. In France, honour loans (Initiative France, Réseau Entreprendre) are personal, interest-free and unsecured, and they strengthen the equity a bank looks at.
In practice, non-dilutive financing is most often used as a complement to an equity round, and rarely as the only funding source for an ambitious plan. When a bank loan is part of that mix, the lender will first run five ratios on your financial forecast, starting with debt service coverage, before committing.
3.2 Equity financing (dilutive)
Equity financing means bringing investors into the company’s share capital in exchange for shares. It is the core mechanism of classic fundraising rounds.
Main equity instruments include:
-
Common shares
Standard shares that typically grant:- voting rights,
- rights to dividends (if any),
- a share of exit proceeds.
Simple and easy to understand; common in early rounds.
-
Preferred shares
Shares with additional rights, frequently used by professional investors.
They can include:- liquidation preferences,
- enhanced financial rights,
- anti-dilution protections,
- specific governance rights.
Equity implies immediate dilution, but provides stable capital with no repayment obligation and long-term alignment with investors.
3.3 Hybrid instruments
Hybrid instruments give deferred access to equity: some are debt (convertible notes), others are warrants or future-equity agreements (BSA, SAFE / BSA Air) with no repayment and no interest. They are often used when the company’s valuation is hard to define at the time of investment.
Common hybrid instruments include:
-
Convertible notes
Debt that can convert into equity at a future event (new round, maturity).
Conversion terms typically include:- a discount,
- a valuation cap,
- a maturity date.
-
Warrants (BSA in France, share subscription warrants)
Instruments that grant the right to subscribe later to shares at a predetermined price.
They are often combined with an initial financing. -
BSA Air (France) / SAFE (US)
The French equivalent of Y Combinator's SAFE (Simple Agreement for Future Equity), frequently used in early-stage contexts.
It carries no interest and converts into shares at a trigger event (usually the next round), with a discount and/or a valuation cap.
It defers valuation discussions to a later round while securing the initial investment.
These instruments offer flexibility, but require rigorous legal drafting to avoid future ambiguity.
3.4 How investors view hybrid instruments
From an investor’s perspective, hybrid instruments are often seen as a risk-management tool, especially at very early stages.
Perceived benefits:
- Deferring the valuation discussion.
- Early access to a future equity entry.
- Protection mechanisms in success and failure scenarios.
Key watch-outs:
- Governance clarity before conversion.
- Stacking too many hybrid lines, which can complicate the cap table.
- Misalignment with founders if terms are poorly calibrated.
Experienced investors typically prefer instruments that are simple, readable, and consistent with the company’s trajectory.
3.5 Think like an investor
Whatever instrument you choose, one principle should guide the structuring of the round: think from the investor’s point of view.
An investor will evaluate in particular:
- the rights attached to the securities,
- the liquidity path over the medium to long term,
- the readability of governance,
- the plausible exit scenarios.
An effective structure isn’t the one that maximizes short-term advantage for the founder: it’s the one that durably aligns founders’ and investors’ interests around a shared value-creation objective.
4. After the round: what changes
A fundraising round marks a turning point in a company’s life. It comes with new reporting obligations, with regular monitoring of financial and operational KPIs.
Governance also evolves: decisions become shared and, often, more formal bodies are put in place. Performance pressure increases, as investors expect disciplined execution against the plan.
Finally, from the first round onward, it’s important to anticipate the next one. Building a strong performance track record becomes a key lever to prepare future fundraising rounds and to sustain a long-term growth trajectory.
Conclusion
Fundraising is a structuring act in a company’s journey. It is neither an end in itself nor a miracle solution: it is a lever to execute a clearly identified plan that requires capital aligned with the company’s ambitions.
A successful fundraising process depends on rigorous preparation: precisely estimating needs, building a credible roadmap, selecting the right financing instruments, and understanding investor expectations. Every decision made upstream (amount raised, valuation, security type, and investor rights), has lasting consequences for governance, dilution, and the company’s future trajectory.
It’s equally important to remember that raising capital moves the company into a new phase. Expectations around transparency, performance, and operational control intensify, and the investor relationship becomes a central part of long-term strategy.
Ultimately, a successful round is one that aligns founders and investors around a shared vision, clear objectives, and strong execution. Approached with method and realism, fundraising can become a powerful accelerator of growth and a catalyst for value creation.