Why valuation is a topic in its own right for startups?
A company’s valuation is neither an exact science, nor a simple multiple mechanically applied to a financial metric. It sits at the crossroads of several dimensions:
- theoretical finance and its academic methods,
- the project’s operational credibility,
- and negotiation between stakeholders.
For startups, this exercise is made more complex by strong structural specificities:
- high uncertainty about the future,
- lack of significant financial history,
- information asymmetry between founders and investors,
- extreme dependence on the founding team and its execution capacity.
You will quickly understand that valuation is closely correlated with the financial forecasting exercise. A credible valuation cannot exist without solid, coherent, and shared assumptions.
This is why we strongly recommend starting with our article dedicated to financial forecasting before tackling valuation.
1. What is business valuation?
Enterprise Value (EV) aims to estimate the overall economic value of a company at a given point in time, that is, its ability to generate future cash flows.
This value is distinct from the value of the equity (securities), which takes into account the company's financial structure, notably:
- net financial debt,
- available cash.
It is this second value, the value of the securities, that corresponds to the price actually paid or received in a transaction.
Many leaders discover, often late at the time of a sale, that enterprise value is not the amount they will actually receive.
We will return to this fundamental distinction later with a numerical example.
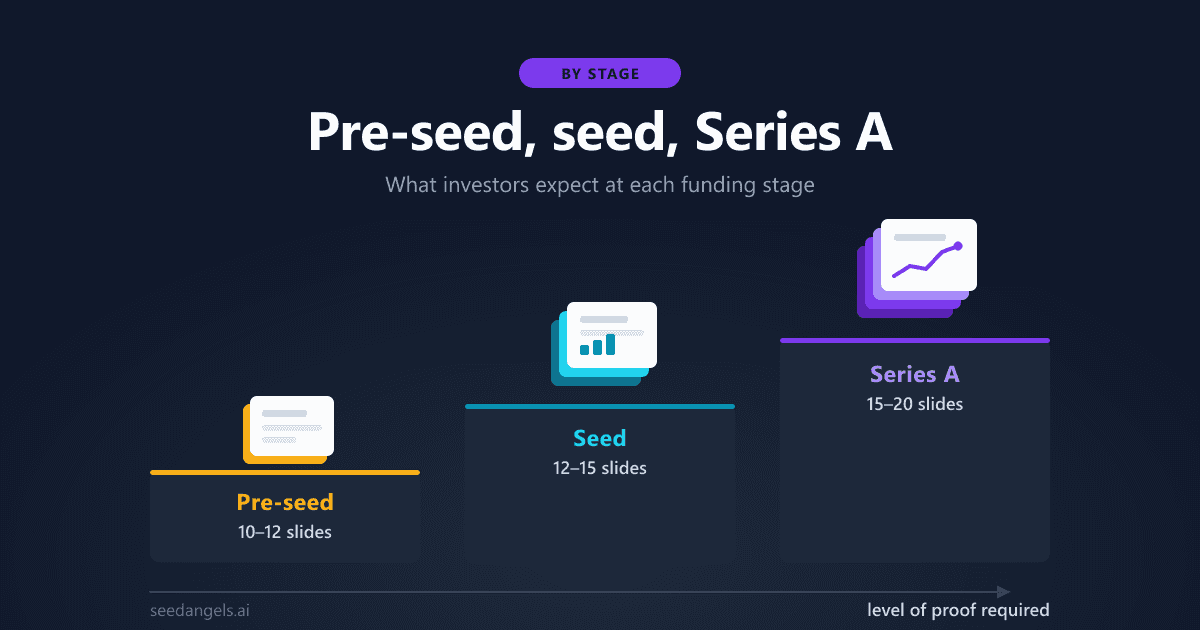
One more thing worth keeping in mind: valuation is never negotiated in the abstract, but against what you have actually proven. The ranges observed and the level of proof required differ markedly from one round to the next: see what investors expect at each stage of fundraising.
2. Classic valuation methods
Before going into detail, it is important to clarify that the methods presented in 2.1, 2.2 and 2.3 are recognized standards for mature company valuation.
They have historically been used in sales, M&A, or restructuring operations for companies that have:
- significant financial history,
- stabilized activity,
- and reasonable visibility on their future cash flows.
Applied to startups, these methods become more delicate to handle, due to the high number of uncertainties around the business model, growth, future profitability, and operational execution.
They remain nevertheless essential points of reference, provided you understand their limits.
2.1 The public comparables method
Principle
This method values a company by analogy with comparable listed companies, using multiples expressed in enterprise value (EV – Enterprise Value).
EV = enterprise value, independent of the financial structure.
Construction
- Select a panel of comparable listed companies
- Analyze multiples (
EV/EBITDA,EV/Revenue,EV/ARR, etc.) - Apply these multiples to the company under study
Advantages
- Public, accessible, and verifiable data
- Method widely understood by investors
- Multiples validated by the market, since transactions operate on this basis
Drawbacks
- Stock prices reflect the price of liquid stakes that can be sold quickly
- Significant gap with startup reality:
- illiquidity,
- absence of a secondary market,
- long holding horizon
2.2 The transaction comparables method
Principle
Valuation is based on the analysis of past transactions involving comparable companies.
Construction
- Identify a panel of transactions
- Select relevant multiples (EBITDA, Revenue, ARR, etc.)
- Apply the multiple to the startup
In SaaS, the multiple applies to ARR, which shifts the stakes onto the quality of that recurring revenue (growth, net retention, gross margin), whose modelling belongs to the SaaS business plan.
Advantages
- Multiples derived from real transactions
- Direct reference to prices actually paid
- Method widely used by professional investors
Drawbacks
- The transactions observed most often correspond to takeovers (majority control)
- Yet, in a fundraising, the stake offered is:
- minority,
- illiquid,
- without control
➡️ This gap can lead to mechanical overvaluation if rights attached to the securities are not taken into account.
2.3 The discounted cash flow (DCF) method
Principle
A company's value corresponds to the discounted sum of its future cash flows.
Construction
- Forecast free cash flows
- Determine the discount rate (WACC)
- Calculate the terminal value
Limits
DCF has many biases, the most important lying in the calculation of the terminal value, which depends on highly subjective parameters:
- long-term growth rate,
- discount rate.
Small variations in these assumptions can produce very significant valuation differences, making the method fragile in a startup context.
2.4 Methods specific to startups
There are many methods dedicated to startup valuation. They share the following traits:
- less academic,
- less standardized,
- therefore more difficult to get buy-in for.
At SeedAngels, we believe the main issue is not the method itself but the ability to build consensus with your investors around the project’s ambition.
This ambition is materialized by a shared financial forecast, whose assumptions are discussed, challenged, and collectively validated.
An accepted forecast lays the foundation for a much more solid valuation basis.
Focus – The VC Method
The Venture Capital Method (VC Method), formalized in 1987 by William Sahlman (Harvard Business School), is one of the most widely used methods at early stage.
It consists of:
-
defining what the company will be worth if it delivers its Business Plan,
-
then bringing that value back to today based on the return expected by investors.
3. Numerical example – Concrete application of the methods
Starting assumption
Your company operates in the sale of travel, with development focused on the French market.
You identify several listed comparable players:
-
Competitor A: American company, national leader – 9x EBITDA
-
Competitor B: French legacy company in decline – 6x EBITDA
-
Competitor C: French company in strong growth, technologically innovative – 8x EBITDA
In addition, a transaction in the sector two years ago indicates:
- a multiple of 7x EBITDA according to one source,
- and 9x EBITDA according to a more reliable source.
Step 1 – Define a range of multiples
These first data points allow you to identify a sector range:
6x to 9x EBITDA
The objective is not yet to explain the gaps, but to set a frame.
Step 2 – Understand the gaps
- The gap between B (6x) and C (8x) is explained by growth
- Comparable A is less relevant:
- larger U.S. market,
- different dynamics
- The observed transaction is relevant, but involved a takeover (majority control)
Summary:
- Decline / minority: 6x
- Growth / minority: 8x
- Growth / majority: 9x
Your company is growing. We prudently use 8x, the multiple of a comparable growing player without a control premium. A trade sale in 5 years could justify up to 9x.
Step 3 – Applying the VC Method
- EBITDA at 5-year horizon: €2m
- Value at exit:
€2m × 8 = €16m
This EBITDA multiple gives an enterprise value. Equity value is obtained by adding cash and subtracting financial debt at that horizon. For simplicity, we assume zero net financial debt in year 5: equity value = €16m. With €3m of net debt it would drop to €13m, and the rest of the calculation with it.
You wish to offer 25% annual return over 5 years.
This 25% rate fits an already-profitable company close to an exit. At seed stage, investors typically target 20–30x their money (80–100% a year over 5 years), which would divide the resulting valuation accordingly.
The present value comes out at approximately:
€5.2m
Step 4 – Pre-money and post-money valuation
Amount raised: €2m
- Post-money valuation (= pre-money + amount raised): €5.2m
- Pre-money valuation: €3.2m
Stake offered to investors:
38% of the share capital
At exit, their investment is multiplied by around 3x, consistent with the return objective, provided no later round dilutes their stake, which is rarely the case. To see how much of that 38% survives one or two further rounds, model them in our round-by-round dilution calculator.
4. Valuation and shareholder rights
The value of a stake depends as much on the headline valuation as on the rights attached to the securities (see article on bylaws and shareholders' agreement):
- veto rights,
- liquidation preferences,
- ratchet clauses,
- exit rights.
Conclusion – Valuation as a dialogue tool
Valuation is neither an absolute truth nor a definitive judgment.
It is a tool for dialogue between founders and investors.
It must be:
- coherent,
- justified,
- understood by all parties.
The only real price is the one at which sophisticated investors are willing to invest, given the project, the context, and the team.
Want to estimate your startup's valuation? Try our free startup valuation calculator to model pre-money, post-money, and dilution scenarios based on the methods described above.